True Finance: Cash Advance

Screenshots
Details
- Rating
- 4.25K reviews
- Version
- 10.6.0
- Developer
- JoinTrueDev
Analysis by Norviv
When an unexpected bill lands between paydays, the first thing I want is clarity rather than a long financial lesson. True Finance: Cash Advance is aimed at that exact moment. It is a free finance app from JoinTrueDev, built around the promise of fast cash without a credit check. I would approach it as a short-term borrowing option to investigate carefully, not as a replacement for steady income or a complete budgeting system.
My first impression is that the app is designed for people who want to move quickly from opening the app to understanding whether a cash advance may be available. That focus can be useful when timing matters, but it also means I would slow down before accepting anything. With borrowing apps, the important part is not only whether an application feels simple; it is whether I understand the repayment amount, timing, and consequences before continuing.
The app sits in the finance category and is rated for Everyone, which makes it approachable for a broad audience. It has passed the one-million-install mark and holds an average rating of 4.4 from roughly forty-seven thousand ratings, with about four thousand two hundred written reviews. Those figures suggest that many people have tried it, although popularity should never be treated as proof that a cash advance is suitable for my own situation.
What to expect before requesting money
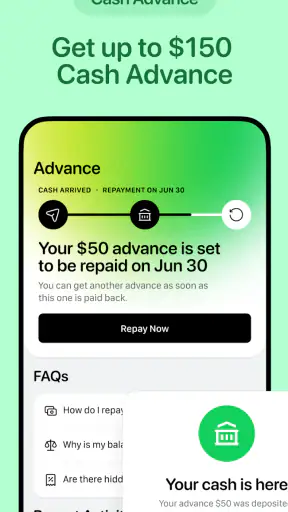
The central idea is straightforward: True Finance presents itself as a way to seek fast cash without a traditional credit check. That can be appealing if a conventional lender is unavailable or if a temporary expense cannot wait. In practice, I would still expect an eligibility process and a review of the offer before any money is accepted. “No credit check” does not mean “no conditions,” and it does not make borrowing cost-free.
The most useful way to view the app is as a screening and application tool for a specific short-term need. It is not the same as a bank account, a savings app, or a debt-management service. If I needed help tracking monthly spending, building an emergency fund, or comparing long-term personal loans, I would use a budgeting tool or speak directly with a bank instead. True Finance makes more sense when the question is narrower: can I access a cash advance, and can I repay it responsibly?
I would also keep expectations realistic about speed. The store summary emphasizes fast cash, but the time from starting an application to receiving funds can depend on eligibility, verification, the selected financial service, and the details of the request. I would not open the app five minutes before rent is due and assume the money will arrive instantly. A better approach is to use it early enough to read every screen without pressure.
There is another important distinction for first-time users. Avoiding a credit check may help someone who has limited credit history, but it does not remove the need to assess affordability. A small advance can still create a difficult gap before the next payday. I would only consider an amount that fits comfortably after essential expenses, not the largest amount that appears available.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
How I would prepare before opening it
Before starting, I would write down the exact expense, its due date, and the amount I can repay without skipping food, housing, utilities, transport, or existing commitments. This simple preparation prevents the app from turning a vague worry into an unnecessarily large request. It also gives me a reference point when reviewing the offer.
I would have my personal and financial details ready, but I would not rush through them. Any finance app deserves the same care I would give a bank form. I would read the purpose of each requested detail, check that the information is accurate, and avoid entering anything while distracted. A wrong digit or outdated account detail can create delays at the worst possible time.
My practical rule would be to treat every advance as a scheduled obligation from the moment I accept it. I would put the expected repayment date in my calendar and leave the repayment amount untouched in my account when possible. That workflow is more important than the app’s quick interface because it determines whether the advance solves a problem or simply moves it forward.
Getting through the first setup without confusion
On first launch, I would begin by confirming that the app is the intended product and that the developer shown is JoinTrueDev. The current version is 10.6.0, and the app supports Android devices running version 7.0 or newer. That broad compatibility is convenient for people using older phones, but I would still install it through the normal official app channel and keep the operating system reasonably maintained.
The setup should be treated as a financial form rather than a casual sign-up. I would read each prompt, check names and contact details carefully, and pause whenever the wording affects eligibility or repayment. If the app presents a consent screen, I would read what I am agreeing to instead of tapping through automatically. The fastest setup is not necessarily the safest setup.
One useful habit is to separate required information from optional profile completion. If a screen offers extra details that are not needed for the immediate request, I would decide whether they genuinely improve my experience before providing them. This keeps the first session focused and makes it easier to remember what information I shared.
I would also inspect the app’s notices before moving toward an offer. The phrase “cash advance” can describe different arrangements, and the important details are the total repayment, any applicable charges, the expected date, and what happens if repayment is late. If those points are not clear in plain language, I would stop and seek clarification rather than relying on a reassuring headline.
The first successful action I would aim for
For a new user, success should not mean accepting money immediately. My first meaningful success would be reaching a clear eligibility or offer screen and understanding the complete obligation. I would compare the amount I requested with the amount I would need to repay, then check whether the timing works with my actual payday and other automatic payments.
For example, imagine my car needs an urgent repair and I am several days away from being paid. I might open True Finance to explore whether an advance is possible. I would enter only the amount required for the repair, review the proposed repayment carefully, and make sure that the future withdrawal would not collide with rent or a utility bill. If the numbers leave my account too tight, the successful decision is to decline, not to force the application through.
This is where the app’s no-credit-check positioning can be both helpful and easy to misunderstand. It may make the initial exploration feel more accessible, but the offer still needs to pass my own affordability test. I would ask myself three questions: do I know exactly what I will repay, do I know when it is due, and will the payment leave enough for essentials? A “no” to any of these would be a reason to pause.
If I do proceed, I would save the confirmation details in a secure place and add the repayment date to my calendar. I would not depend on memory or assume that an app notification alone is enough. I would also check my bank balance before the due date, because a cash advance can become expensive or stressful if the repayment attempt meets insufficient funds.
Small workflow choices that make a real difference
A less obvious advantage of handling the process deliberately is that it creates a record of my decision. I would note the requested amount, the final repayment figure, and the date in a private note. This makes it easier to compare the advance with alternatives such as asking a bill provider for more time, using an existing emergency fund, or choosing a conventional loan with clearer long-term terms.
I would also use the app for one need at a time rather than stacking advances to cover earlier advances. That is a crucial trade-off. A short-term tool can be manageable when it addresses a single, defined gap; it becomes dangerous when it is used repeatedly to maintain ordinary monthly spending.
Another practical tip is to test the full repayment in my budget before accepting the offer. I would subtract it from my expected post-payday balance, along with fixed bills and groceries. Looking at the remaining amount is more revealing than judging the advance by its size alone. A modest advance can still be unaffordable if the next pay cycle is already committed.
Common points that can cause hesitation
The first source of confusion is the wording around credit checks. I would not interpret it as a guarantee of approval, a guarantee of funds, or a promise that borrowing will have no effect on my finances. It describes the approach advertised by the app, while eligibility and the final terms still matter. Anyone who needs certainty should read the actual offer rather than relying on the store summary.
The second issue is the meaning of “free.” The app itself is free to install, but that does not automatically mean every financial service or advance connected with it has no cost. I would distinguish between the app’s download price and the financial terms of a transaction. Before accepting, I would look for the total amount owed and any fee or charge shown during the process.
Another point worth checking is repayment timing. A user may think, “I get paid next week,” while the repayment schedule uses a different date or depends on account processing. I would verify the exact date displayed in the final terms and make sure my income arrives before then. If the timing is uncertain, I would not treat the advance as safe simply because the amount is small.
Some people may also wonder whether the app is suitable for building credit. I would not use it with that expectation. Its appeal is quick access without a traditional credit check, not a clearly stated long-term credit-building strategy. Someone trying to establish a credit history would be better served by a product specifically designed and explained for that purpose.
Privacy is another reason to slow down. Any application involving financial information deserves a careful reading of its privacy and consent screens. I would use a secure device, avoid public Wi-Fi when entering sensitive details, and make sure the phone is protected with a lock. These are sensible precautions for True Finance because the task involves personal financial information, not merely entertainment preferences.
Where the app may not be the right choice
I would skip True Finance if the expense is recurring. If I need an advance every month for groceries, transportation, or household bills, the problem is larger than a single cash gap. In that situation, I would look at a spending plan, negotiate bills, seek community assistance, or speak with a trusted financial counselor. Repeated short-term borrowing can hide the underlying shortfall.
I would also compare alternatives when I have time. A bank or credit union may offer a personal loan with a longer repayment period, while an employer-based wage-access option may fit someone whose workplace provides it. Asking a service provider for a payment arrangement could be cheaper than borrowing. The right choice depends on the complete cost and repayment pressure, not on which option opens fastest.
Someone who dislikes reading financial terms on a phone should be especially cautious. The app may make the application feel convenient, but convenience can encourage quick acceptance. I would recommend using a larger screen or taking notes if the details are difficult to review. If the final obligation remains unclear, choosing a more transparent alternative is sensible.
On the other hand, the app can be useful for a person who has a defined, short-lived emergency, understands the repayment date, and wants to explore an option without a traditional credit check. The key is that the user remains in control of the decision. Fast access is helpful only when the repayment plan is equally clear.
What I would do after the first application
After completing the first session, I would not keep checking the app out of habit or treat an available amount as extra income. I would use it only when a genuine need arises and reassess the budget each time. If I accepted an advance, I would monitor the account around the repayment date and keep enough money available for both the advance and essential bills.
I would also review the transaction afterward. Did the money arrive when expected? Was the repayment amount what I understood? Did the process create any unexpected pressure? These questions help me decide whether the service is appropriate for future emergencies. A smooth application does not automatically make repeated use wise.
Because the app has been available since December 21, 2022, and continues to receive updates, I would check the current screens and terms every time rather than assuming a previous experience remains identical. The installed version can change, and financial details should always be judged from the offer in front of me. That is especially important when an app’s main appeal is speed.
For first-time users, my recommended path is simple: install carefully, complete the setup accurately, request only what the specific expense requires, read the full repayment terms, and set a reminder immediately. If the numbers do not fit, close the application without accepting. Declining an unsuitable advance is a successful financial decision.
Overall, True Finance: Cash Advance is most convincing as a focused way to explore short-term cash access, particularly for someone who may not qualify for a traditional credit check. Its free availability, broad Android support, and clear cash-advance focus make it easy to consider, while the large user base gives it a level of familiarity among finance apps.
My recommendation comes with a firm condition: use it for a specific emergency, not as a routine bridge between paydays. The app can help me investigate an option quickly, but it cannot make an unaffordable repayment affordable. If I understand the total cost and timing and have room in my budget, it may be worth considering. If I need ongoing financial support or a long-term borrowing solution, a bank, credit union, budgeting service, or debt adviser would be a better fit.
Frequently Asked Questions
01What is True Finance: Cash Advance, and how does it work?
True Finance: Cash Advance is a financial app designed to help eligible users review their financial information and explore potential cash-advance options. After creating an account and providing the requested details, the app may evaluate your profile and present available offers. Approval, advance amounts, fees, repayment terms, and eligibility are not guaranteed and can vary by user and location.
02Can everyone qualify for a cash advance through True Finance?
No. Access to a cash advance is not guaranteed for every applicant. Eligibility may depend on factors such as your identity, income, banking activity, account history, state or country of residence, and other information reviewed during the application process. Before accepting anything, carefully check the offer details, including the amount you will receive, any applicable fees, the repayment date, and the total amount you may owe.
03Are there fees or interest charges when using True Finance: Cash Advance?
Costs can depend on the specific service, offer, and terms shown to you in the app. Some financial products may include membership charges, transaction fees, expedited-transfer fees, or other costs, while an offer may also involve different pricing conditions. Read all disclosures carefully before proceeding, and do not assume that an advertised advance is free. The final agreement should explain the complete cost.
04How quickly can I receive money, and how is repayment handled?
If you are approved and accept an available offer, delivery speed may depend on the selected transfer method, your bank, weekends, holidays, and verification requirements. Standard transfers can take longer than expedited options, which may involve an additional fee. Repayment is normally connected to the terms presented before acceptance, so confirm the scheduled date, payment method, and consequences of a late or failed payment.
05Is True Finance: Cash Advance safe to use, and what personal information does it request?
As with any finance app, use caution before submitting sensitive information. The application may request personal, contact, employment, identity, and banking details to provide its services or assess eligibility. Download it only from an official app store, review the developer name and privacy policy, and grant only permissions that make sense. Never share passwords, verification codes, or banking credentials outside the app’s secure process.


